
Trump's $500 User Fee Flim-Flam brings up several more things that make you go "hmmmm..."
Wed, 10/07/2026 - 3:28pm
About a month ago, Donald Trump announced another one of his shameless voter-bribe attempts in a desperate attempt to salvage what's expected to be a disastrous midterm election for Congressional Republicans:
RETURNING BIDEN OVERCHARGES TO WORKING FAMILIES: Today, President Donald J. Trump announced that the federal government will return to the American people hundreds of millions in Obamacare overcharges, collected by the Biden Administration, by issuing refunds of $500 per person to nearly 1 million Americans in 30 states. Today’s actions directly refund the Americans most exposed to the higher costs imposed by the Biden Administration’s gross mismanagement of Obamacare.
At the time, I explained what this was all about; the short version is that Trump is essentially stealing around $475 million from HealthCare.Gov's budget and using it to make cash payments of $500 apiece to roughly 950,000 ACA enrollees who are no longer eligible for federal ACA tax credits...thanks to Congressional Republicans and Trump himself allowing the enhanced subsidies to expire last December.
In my prior piece I noted that most of Trump's claims were either flat-out lies or disingenuous at best: He claimed that the Biden Administration was "overcharging" enrollees for HC.gov operational expenses and that he (Trump) was lowering the fee in order to generously pass the savings back to the enrollees; in reality, the Biden Admin is the one who did most of the fee lowering, and in fact the fees were lower during Biden's term than Trump's first term in office when adjusted for inflation.
Ultimately, I noted that Trump had effectively jacked up the average premiums for higher-income ACA enrollees by thousands or even tens of thousands of dollars by letting the subsidies expire, and was now "giving back" a tiny fraction of that:
Trump is playing one of the oldest con games in history: He took $100 out of your back pocket and wants you to thank him for putting $10 back in.
However, as you probably guessed, there's even more to this story.
First of all, here's Jonathan Cohn of The Bulwark's piece on it, which among other things notes that, like almost everything else the Trump Regime is doing, sending out these checks in the first place is almost certainly highly illegal on the face of it:
AN EVEN BIGGER CONCERN for Keith and others is the legal authority for these checks—authority that, she and others told me, may not exist. The relevant passage in the statute says user fees exist to “support [exchange] operations” and explicitly prohibits the “wasteful” use of funds. Regulations from the Department of Health and Human Services give examples of activities that the user fees could pay for, such as “provision of consumer assistance tools” and “consumer outreach and education.”
“This is not a slush fund for the administration to use in whatever way that it wants,” Keith said.
The administration did not cite a legal authority for the checks when announcing them. And while an administration official did respond to some of my queries, by describing how the rebates work and who was getting them, the official did not address my questions about what legal basis there is in the Affordable Care Act to justify the checks.
Nor did the official respond to a follow-up question pressing for an answer.
In addition to this, there's two other important factors to consider which didn't make it into my original post.
First of all, there's the question of the number of people receiving these "rebate checks." According to Becker's Payer Issues:
The Trump administration has begun sending $500 checks to more than 950,000 people in 30 states it says were overcharged through the ACA’s federal exchange, according to information an administration official shared with Becker’s.
...Texas has the most recipients at 139,000, followed by Florida at 127,900, Ohio at 65,700, North Carolina at 58,200, Wisconsin at 56,200 and Michigan at 55,100, according to administration estimates. Mississippi has the fewest at 2,800.
4. Recipients are primarily people above 400% of the federal poverty level, though the group includes some between 100% and 400% who did not receive subsidies. Some families with more than one affected person will receive multiple checks or direct deposits.
Now, as I explained earlier, the fact that the checks are only going to enrollees in 30 states instead of all 50 is not, in & of itself, eyebrow-raising: the other 20 states (+DC) operate their own individual ACA exchanges with their own funding systems (whether via user fees, targeted taxes or whatever); this only applies to the 30 states which utilize HealthCare.Gov as their enrollment platform (as an aside, this will drop to 29 next month when Oregon becomes the 22nd state to transition off of the federal exchange onto their own platform).
However, since nearly all of the states which have their own ACA exchanges also happen to be blue states (exceptions: Georgia, Idaho, Kentucky & Nevada), this also means that, by definition, nearly all of the 30 states which are seeing the $500 checks happen to be either red or swing states...a nice ancillary benefit for Trump/Republicans, as it happens.
Here's where the math does begin to get problematic, however:
According to the Trump Administration's own data, there only around 561,000 people projected to earn more than 400% of the Federal Poverty Level (FPL) selected ACA exchange plans in the 30 states on the federal exchange during the 2026 Open Enrollment Period (OEP) last winter...far less than the "more than 950,000" mentioned in the Becker's article ("nearly 1 million" via the Trump Regime press release). Even if you also include the additional ~340,000 with "Unknown/Other" incomes, that only gets you to 901,000.
Now, the Becker's article does clarify that some of those getting the checks are enrollees below 400% FPL who also didn't receive subsidies for whatever reason, which presumably explains the missing ~49,000 or so.
However, there were around 1.53 million of those in HC.gov states who signed up during OEP total who didn't qualify for subsidies. If you subtract the 901,000 over 400% FPL, that leaves around ~630,000 enrollees below 400% FPL who didn't qualify for them; and of those, around 132,000 didn't qualify because they earn less than 100% FPL, which leaves around ~498,000 enrollees who live in HC.gov states, are projected to earn between 100 - 400% FPL, and who didn't qualify for federal subsidies this year...around 10 times as many as the ~49,000 figure.
There's also a second, even more important factor to consider, however: All of the numbers above are based on plan selections during the Open Enrollment Period, not actual effectuated enrollees.
Nationally, OEP plan selections across the 30 HC.gov states totaled 15,771,397...but actual effectuated enrollment as of January was only 13,605,898. That's 13.7% fewer enrollees (-2,165,499).
I have no idea what the distribution of those "lost" enrollees is, unfortunately (CMS still hasn't posted more recent demographic breakouts of 2026 enrollment data), but assuming the drop is proportional across the various income brackets, that means there were only around ~777,000 over 400% FPL plus another ~430,000 between 100 - 400% FPL who didn't receive subsidies. If you assume all 777,000 over 400% are part of the ~950,000 receiving the checks, that means that the remaining ~173,000 are unsubsidized enrollees earning between 100 - 400%...which would still leave around ~257,000 of that group unaccounted for.
What about at the state level? The Becker's article only lists a few states, but of those, here's what it looks like:
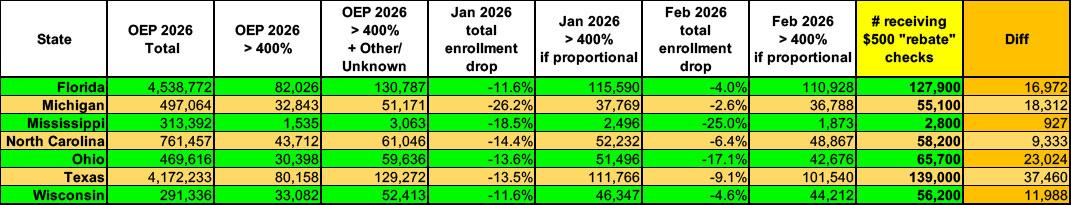
Effectuated enrollment since January has only continued to drop--it fell by another million people (5.1%) from January to February, and since then it's continued to drop nationally every month judging by all the data I have so far.
I realize some of the math can get confusing, but the bottom line is that this suggests (not proves) that either the Trump Regime is lying about the "more than 950,000 enrollee" figure or that a significant chunk of those 950,000 checks of $500 apiece are going to people who either a) are receiving subsidies after all; b) signed up but were never actually effectuated; or c) were only effectuated for a month or two of the year.
I should also note that none of this even gets into the question of whether or not any of the 760,000 ACA exchange enrollees who the Trump Regime kicked off their healthcare coverage last month are among those receiving the checks...in some cases due specifically to them allegedly earning more than 400% FPL.
This would be incredibly ironic given that the whole reason cited for terminating those enrollees was that they were "enrolled improperly" or "fraudulently."
Finally, there's one more twist to this enigma which also ties into the "fraudulently enrolled" story:
There are millions of Americans who may earn around 400% FPL each year, but whose income can range widely from one year to the next--they might earn more than 400% one year and less the next. When you apply for ACA exchange coverage you have to project your estimated income for the upcoming year. If they project an estimated 2026 income below 400% FPL but end up actually having a MAGI income over 400% FPL, that isn't fraud.
It's literally how the ACA is designed to work, and it's no different than someone who's self-employed trying to project their quarterly taxes for the following year: If you overestimate, you end up getting a tax refund. If you underestimate, you have to pay more in taxes.
The same applies here: If you project your income to be under 400% FPL but it turns out to be over 400% FPL, the worst that happens is that you have to pay back the full amount of federal ACA subsidies when you file your taxes the next spring.
In fact, there's several perfectly legal ways of pushing your MAGI income below 400% FPL:
It's also worth noting that contributions to a pre-tax retirement account and/or a health savings account will reduce your MAGI, which is what the IRS uses to determine your premium tax credit eligibility. (Note that in order to contribute to a health savings account, you must have coverage under an HSA-qualified high-deductible health plan.) You should consult your tax advisor to learn more about this.
Even if you gross more than 400% FPL, there are several ways of knocking it below the cut-off threshold...and some of these can even be done after the end of the calendar year, as long as they're done before you file your taxes for that year.
Guess who's part of this population? Yours truly: My wife and I projected our 2026 MAGI income to be below 400% FPL, and we hope to keep it below that, but given how variable our incomes are and the fact that a large chunk of our household income comes in during the. holiday season, we may not know for certain whether we'll end up over or under 400% FPL until after the end of December.
If it's over 400%, fine; we'll have to pay back the full subsidy amount, which would suck, but that's how the law works now...but it also means that we won't receive the $500 checks, because the HC.gov system currently has us down as qualifying for subsidies. If that happens, we won't receive the rebate check even though we're "supposed" to due to not qualifying for subsidies.
Conversely, there may also be some enrollees who are currently projected to earn more than 400% FPL this year who will turn out to earn less than 400% FPL and will thus become eligible for a substantial lump-sum subsidy when they file their taxes next spring. THOSE folks are receiving $500 apiece even though they aren't "supposed" to due to qualifying for subsidies in the end (admittedly there's probably very few cases like this).
In the end:
- The $500 "rebate" scheme is being done in a way which almost exclusively targets Americans living in red & swing states;
- The recipients are being selected according to sloppy, arbitrary means;
- It still only cancels out a small fraction of the economic damage caused by Trump/Republicans to begin with; and...
- It's likely illegal in the first place
Advertisement


